Should I Refinance my Mortgage?
Taking advantage of a lower rate can generate substantial interest savings over 30 years, but you should try to shoot for a 2% lower rate.
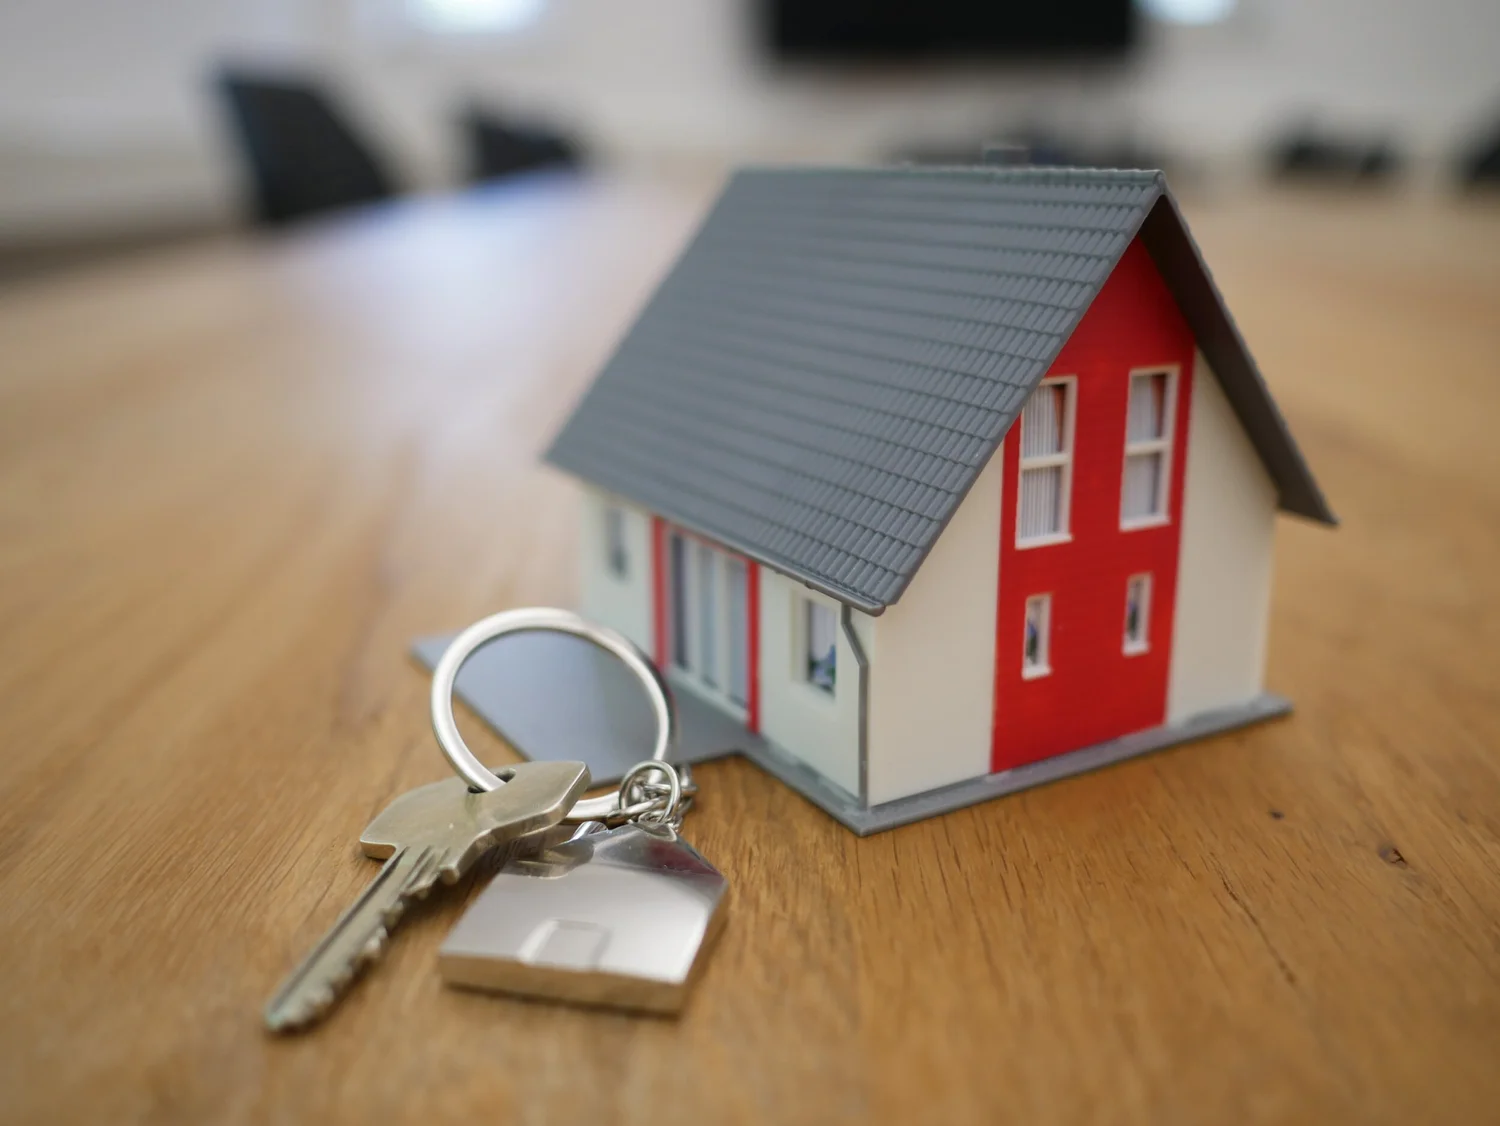
Refinancing a mortgage is the process of taking out a new mortgage to replace your current one. Your reasons to do so may be varied, but most commonly include:
- Reducing your monthly payment.
- Taking advantage of your home's increase in value by increasing your mortgage balance to take 'cash out' to pay off other debt like credit cards, auto loans or home improvement.
- Reducing your term. For example, you can save a tremendous amount of interest by refinancing your 30 year mortgage to a 15 year mortgage.
If you're simply thinking of refinancing to replace your current rate with a lower rate (known in the industry as a 'rate and term refinance'), you will likely end up with lower monthly payments. But, because there is no free lunch, the lower payment comes at the cost of a higher principal balance to cover your refinancing closing costs, in addition to resetting your loan term back to 30 years. So for example, if you're 3 years into a 30 year mortgage, not only will your balance increase, but your term will reset to 30 years. If lower payments are important to you then it makes financial sense, but unless your interest rate falls by at least 2%, usually you're worse off after considering the term reset to 30 years and the added closing costs on your current balance.
With respect to interest rates, they tend to go lower with bad economic news. The pandemic has driven rates substantially lower. Taking advantage of a lower rate can generate substantial interest savings over 30 years, but you should try to shoot for a 2% lower rate than your current rate and shop around for the best deals on closing costs.
Some lenders will offer to pay your closing costs by offering a slightly higher rate. When comparing offers, rather than focusing on rate and total closing costs, it is more important to compare APRs. APRs are required to be disclosed by all lenders and are what I call a 'truth serum' when comparing complicated offers with different rates and closing costs. If you compare APRs, the lowest one is guaranteed to be the best for you long term.
If you put down less than 20% on your home and have owned your home under 5 years you may be required to provide Private Mortgage Insurance (PMI) to the lender. It may make sense to wait until the value of your home increases so the loan amount does not exceed 80% of its value. It's important to recognize your lender won't automatically remove Private Mortgage Insurance from your loan. If you feel your property has appreciated to where your loan balance is 80% or under its current value, it's worth looking into a refinance or asking your lender to drop the PMI.
Right now, it is a great time to refinance if it makes sense to take advantage of the low interest rates currently offered. However, it's important you consider all the pros and cons before simply chasing a lower rate.
This article is for general information only and is not financial advice.
Why Do Business Reviews Work?
Social proof is a powerful weapon of influence where we see the experiences and actions of others just like us as an indication to perceive a product or service as more desirable.
Read →
What it Takes to Be a Successful Entrepreneur
Entrepreneurs are optimists by nature. This immunity to failure is at the heart of the resiliency present within the DNA of all successful entrepreneurs.
Read →
The Power of Generating Social Proof
A positive review is vitally important to a marketing campaign because it increases trust and engagement via social proof.
Read →